Flash Sale on Select Conference Locations Ends Friday – Up to 40% off
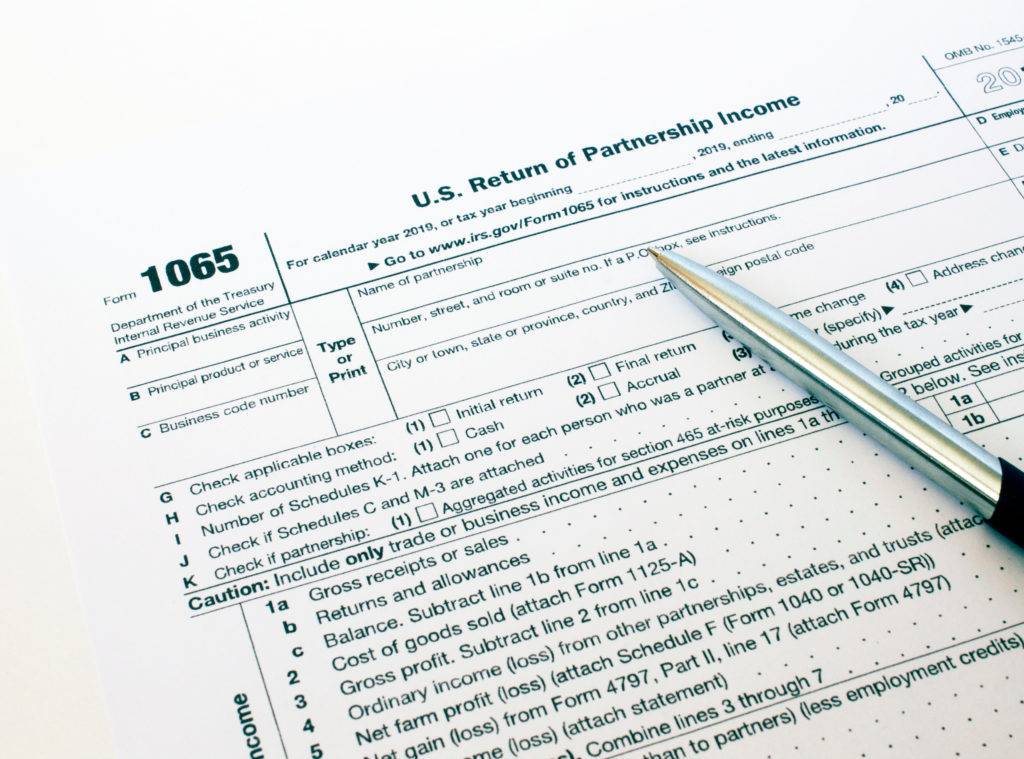
If you’ve had a chance to review the draft 2022 Partnership Instructions for Schedules K-2 and K-3 (Form 1065) the IRS dropped yesterday, you may have noticed it came bearing good news. Not in like an angel way or anything but in that special IRS-exception way.
Scroll down to item 1 on page 3 of the draft instructions, and you’ll see a domestic filing exception for Schedules K-2 and K-3. The instructions state that a domestic partnership need not file the Schedules K-2 and K-3, or furnish to a partner the Schedule K-3 (except where requested by a partner after the “1-month date”), if each of the four listed criteria are met with respect to the partnership’s
tax year 2022. Most notably, the schedules do not have to be filed if no more than $300 of foreign income taxes allowable as a credit under section 901 are treated as paid or accrued by the partnership.
You asked; we listened. After you take a look at the draft instructions, keep an eye out for a related Western CPE course coming soon. Together we’ll walk through these new draft 2022 instructions and demystify the filing of the (new-ish) Schedules K-2 and K-3 for Form 1065.
Stay updated with more breaking tax-related developments by subscribing to Tax Bytes with Jessica Jeane, J.D.
Subscribe to our news, analysis, and updates to receive 10% off your first purchase of an on-demand digital CPE course.