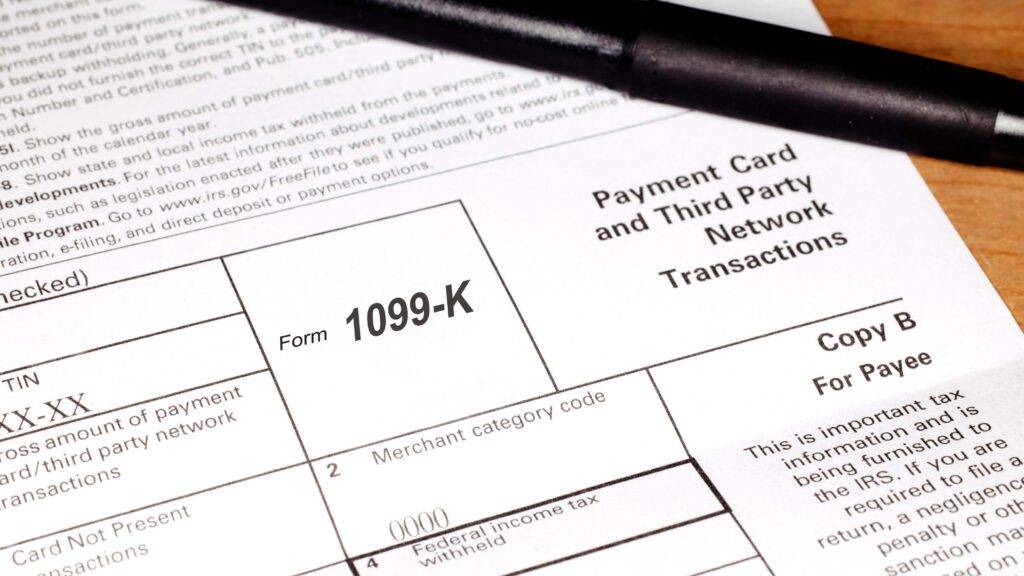
Treasury and the IRS have finalized regulations telling third party settlement organizations (TPSOs), the payment apps and online marketplaces that settle payments between buyers and sellers, when backup withholding begins on payments to sellers. The regulations took effect August 10, 2026, but apply to payments made in calendar years beginning after December 31, 2024, so 2025 payments are covered.
OBBBA amended §3406(b) to tie backup withholding on third party network transactions to the restored Form 1099-K de minimis threshold in §6050W(e): more than $20,000 of gross payments and more than 200 transactions in the calendar year. Crossing those thresholds makes a payment reportable. It does not, by itself, require backup withholding. A separate §3406(a) trigger must also exist, most often the seller’s failure to furnish a correct TIN after the platform asks for it.
Once both thresholds are exceeded, the platform withholds on the entire transaction that pushes the seller past the later of the two thresholds and on every reportable payment after it that year. Earlier payments are not reached. The rate is the fourth lowest rate under §1(c), currently 24%.
If the platform made reportable payments to the seller in the preceding calendar year, the thresholds do not apply in the current year, and a seller still subject to backup withholding is withheld on from the first payment. The rule stops applying only after a calendar year with no reportable payments to that seller.
A seller who ignores a platform’s TIN request can lose 24% of platform receipts for the rest of one year and from the first dollar of the next, recoverable only as a credit on the return. Confirm that clients who sell through payment apps or marketplaces have furnished a correct Form W-9 to each platform and remind them that neither a missing Form 1099-K nor the absence of withholding changes whether the income is taxable. For the full mechanics and worked examples, see our earlier eTax Alert, One Missing W-9 Can Trigger Two Years of Backup Withholding.
For more tax developments, visit the Western CPE eTax Alerts page at westerncpe.com/etax-alerts/.
Subscribe to our news, analysis, and updates to receive 10% off your first purchase of an on-demand digital CPE course.